 Alex Morgan
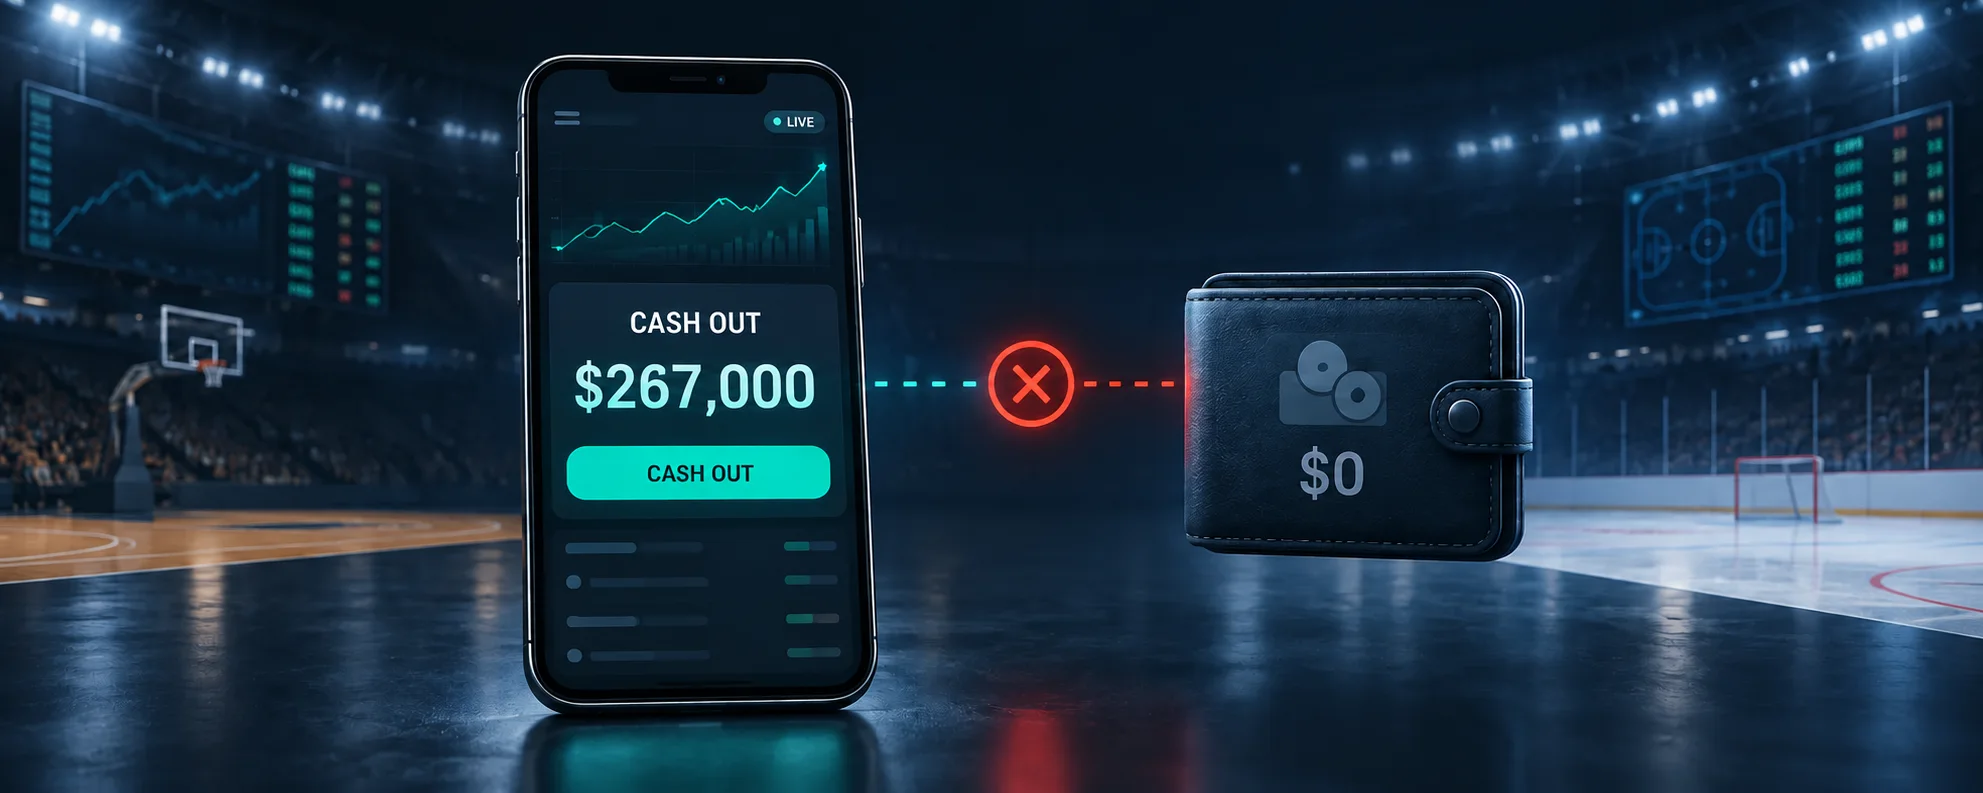
A bettor accepted a $267,000 Cash Out, but the transaction never happened
A sportsbook app offered to settle a parlay early for around C$380,000, approximately US$267,000. The bettor immediately tapped Accept, but the money never reached the account: automated verification rejected the transaction because the odds had already changed.
Four minutes later, the app displayed a new amount of almost C$100,000, or about US$70,000. The bettor tried to accept again. That transaction also failed. The final leg of the parlay lost, leaving the customer with $0.
On October 6, 2026, the Alcohol and Gaming Commission of Ontario (AGCO) imposed a C$200,000, approximately US$141,000, penalty on theScore Bet. The regulator concluded that neither Cash Out opportunity could be obtained in the way it had been presented.
The story raises a more interesting question than the size of the penalty: when is a Cash Out amount on screen a real offer, and when is it only a preliminary quote that the sportsbook may still reject after the customer taps the button?
The AGCO release states all amounts in Canadian dollars. US dollar equivalents are approximate and use the Bank of Canada exchange rate for October 6, 2026: C$1 ≈ US$0.704.
A parlay with a potential payout above C$1 million
On March 14, 2025, a theScore Bet customer placed C$1,000 on a multi-leg parlay covering NHL, NBA and NCAA basketball games taking place that day.
Had every leg won, the potential payout would have exceeded C$1 million. The AGCO did not disclose the exact number of selections, the markets involved or the odds for each leg.
Once every leg but one had won, the app displayed a Cash Out of approximately C$380,000. It was not merely an informational estimate next to the bet: the interface allowed the customer to accept the offer.
The bettor did so immediately. However, an automated check took place between the displayed amount and the completion of the transaction. The odds changed during that interval, so the system rejected the request.
Four minutes later, a second offer appeared, this time for less than C$100,000. The customer again tapped Accept, but the bet was not settled. The remaining leg then lost and the entire parlay was graded as a loss.
How Cash Out is executed technically
Cash Out allows a bet to be settled before its final result is known. The sportsbook estimates the current probability of the remaining outcomes and offers an amount at which it is willing to take the risk back early.
That price changes constantly. It may be affected by:
- new events in the games;
- changes in the odds;
- markets being suspended or reopened;
- changes in available data;
- internal limits and the state of the risk system.
There is therefore usually a separate confirmation stage between the button appearing and the money being credited. In simplified form, the process is:
quote calculation → Cash Out display → customer taps Accept → revalidation → confirmation and credit.
Revalidation is reasonable in itself. In live betting, a price can change within a fraction of a second, while the customer interface, pricing server and settlement system do not update at precisely the same time. Without another check, a sportsbook could repeatedly execute stale offers.
The problem begins when a customer sees a specific amount and an active button, accepts immediately, yet has no practical ability to obtain the displayed price.
A displayed price and an executable price are not the same
On financial markets, an interface quote does not always guarantee execution of an entire order either. By the time an order arrives, the price may have changed or the available volume may have disappeared.
But a trading-venue user usually understands the structure of the transaction: the order book, order type, order status and final execution price are visible. Cash Out in a sportsbook app looks much simpler: a ready offer with one amount and an Accept button.
That is why the burden of an internal revalidation cannot be shifted entirely to the customer. If the amount is preliminary, the interface should say so clearly. If an offer is no longer available, it should disappear or update promptly. And if the sportsbook retains the right to reject the price after the customer taps Accept, the customer needs to understand when the action becomes finally accepted.
The situation has a limited resemblance to last look on some trading venues, where a price provider gets a final opportunity to check a quote after the customer has submitted an execution request. It is not a complete technical analogy, but the conflict is similar: one party believes it accepted the displayed price while the other does not yet consider the transaction complete.
What the operator actually violated
The AGCO did not say that a sportsbook must guarantee every Cash Out amount regardless of market movements. The regulator focused on how the opportunity was presented to the customer.
Standard 4.07 of Ontario’s internet gaming standards prohibits misleading players about a game, possible outcomes, prizes or features, including describing opportunities that cannot actually be achieved.
After its review, the Registrar concluded that neither Cash Out offer was achievable as presented. Score Media and Gaming Inc., the operator of theScore Bet, received a C$200,000 penalty, the maximum monetary penalty available to the regulator for this violation.
The operator may appeal the decision to the Licence Appeal Tribunal. At publication, the penalty is therefore a regulatory decision that may still be challenged.
The penalty does not mean the bettor received C$380,000
The most important distinction is that the AGCO penalized the operator for presenting misleading Cash Out opportunities but did not award the bettor C$380,000 or C$100,000.
The regulator expressly noted that enforcement against the operator and the customer’s individual dispute-resolution options are separate processes. The public release does not say whether the bettor later received compensation, a stake refund or any other payment.
Nor can we automatically conclude that the first amount had to be paid. That would require a separate determination of the offer’s contractual status, the exact moment of acceptance, the applicable Cash Out rules and the dispute process available to the customer.
When is an offer actually accepted?
From the customer’s perspective, the logic is straightforward: if a sportsbook displays C$380,000 and an active Accept button, tapping it should either complete the transaction or immediately and clearly explain that the price has changed.
For the sportsbook, the process is more complicated: the displayed amount may have been calculated from market conditions that became stale before the request arrived. The system therefore wants to check the price again.
Both perspectives are technically understandable. But the operator designs the interface and defines the confirmation sequence. A customer should not have to guess whether the button accepts an offer or merely asks the sportsbook to consider it again.
The AGCO announcement does not reveal which specific part of the system failed. The cause could have been a delay in updating the displayed amount, revalidation taking place too late, the absence of a brief price lock or another feature of the execution workflow. The regulator did not publish technical logs or conclude that the Cash Out mechanism as a whole had been implemented incorrectly.
What was established is narrower: the interface twice presented a specific amount as available for acceptance, yet the execution process did not allow either amount to be obtained. The regulator considered this mismatch between what the product appeared to promise on screen and what the system could execute misleading.
A properly designed interface can address this in several ways:
- remove stale amounts quickly;
- state clearly that the price is confirmed only after the button is tapped;
- when the price changes, display the new amount and request separate confirmation;
- hold the offer for a short, clearly stated period;
- show an unambiguous transaction status rather than failing silently.
The theScore case does not show that price revalidation is inherently wrong. It is necessary protection against stale live odds. But if an additional sportsbook confirmation is required after the customer taps the button, the interface should not present the preliminary amount as an already executable transaction.
Cash Out is not merely a number generated by a model. It is an offer, an interface and an execution mechanism at the same time. A system can retain revalidation and other risk controls, but the meaning of the button on the frontend must match what the backend can actually execute. According to the regulator, that alignment was missing in this case.