 Alex Morgan
When Hundreds of Small Bets Create a Big Problem for a Sportsbook
A sportsbook mispriced an esports market. A customer noticed the price and shared it. The information spread through forums and WhatsApp groups, and within minutes the market received many small bets on the same outcome.
Senior betting consultant Jon Russell described this pattern in an iGamingBusiness article about trading teams in African markets. Instead of one large wager from a professional bettor, a bad price can be used simultaneously by hundreds of customers staking small amounts.
This was not a publicly identified WhatsApp channel or a documented single incident. The original account names neither the group, sportsbook nor match, and gives no exact number of bettors, price or financial result. It is an industry observation from someone who has worked with these markets.
The mechanism is nevertheless clear. One message in a private group can contain the sportsbook, market and attractive price. Members do not need to coordinate stakes: each independently repeats the bet from their own account. The operator cannot see the conversation and discovers the spread only from the incoming order flow.
A $20 bet looks ordinary. Hundreds of identical decisions in a few minutes create exposure that bears little relation to the size of any single bet.
One conspicuous bettor is easier to control
Sportsbooks assess more than selection and stake. Account history, performance against the closing line, market choice and other signals can affect how informed a customer is considered.
When a known professional requests a large stake on an early or illiquid market, the operator immediately sees a meaningful event. It can accept only part of the stake, move the odds, lower the available limit or suspend the market for review.
Hundreds of $10 or $20 bets look different. Every account may appear ordinary and every amount may fit the standard limit. If accounts are assessed in isolation, the first bets may not look dangerous. The issue appears at market level: request frequency jumps, money concentrates on one outcome and potential payout grows unusually fast.
How one price reaches hundreds of people
In many African countries betting is more social than a mobile interface suggests. Customers discuss events in WhatsApp and Telegram, follow tipsters and forward ready-made bet slips.
Booking codes are especially important. A sportsbook stores a group of selections under a short code; another customer enters it and receives the prepared slip, needing only to check the current prices, enter a stake and confirm.
The same mechanism can distribute one attractive price. Users no longer need to discover the market and evaluate the odds independently.
This should not automatically be confused with a syndicate. A professional group may coordinate accounts, stakes and timing, then share the result. In an open channel people often see someone else’s selection and independently copy it. Sharing a wager alone does not prove fraud, coordination or a breach of rules. Economically, however, the operator may still acquire one concentrated position.
What happens to aggregate liability
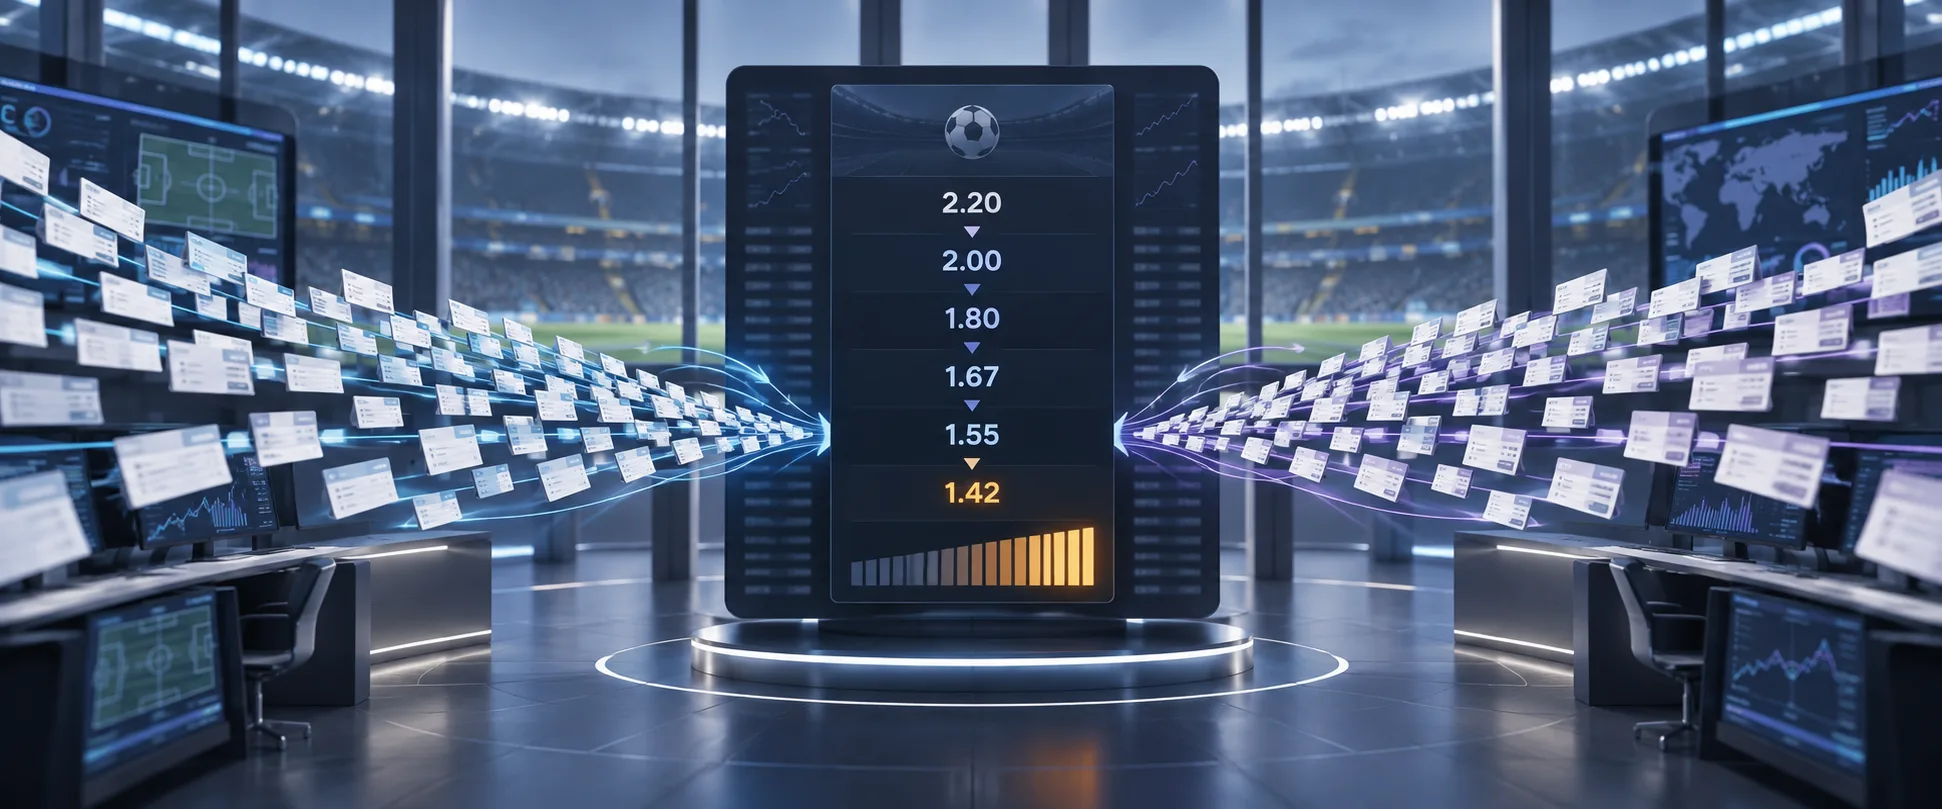
Suppose the justified market price is about 1.80, but a sportsbook mistakenly offers 2.20.
If one customer stakes $2,000, the potential payout is $4,400 including returned stake, or a net $2,400 outflow if the bet wins.
Now suppose the price reaches several groups and 400 customers stake $20 each:
- total stakes are $8,000;
- potential gross payout reaches $17,600;
- net outflow above stakes reaches $9,600 if the outcome wins.
The $17,600 figure is a deliberately simplified upper-bound scenario in which all 400 bets are accepted at 2.20. In practice the system will probably shorten the price, reduce the available amount or suspend the market. Not everyone will necessarily receive the original odds.
The risk is how many wagers are accepted at the wrong price before the line is corrected. If information travels faster than repricing and controls, even a stream of small bets can create material exposure.
$17,600 is not automatically a sportsbook loss. Money may also have been accepted on the other side, and the financial result depends on its distribution across all outcomes. The example shows that a per-bet limit does not cap aggregate liability when many accounts receive the same price.
There is also a mathematical cost. Odds of 1.80 imply roughly 55.6% probability before margin. At that probability, offering 2.20 gives the sportsbook negative expected value. The more volume accepted at that price, the more costly a slow reaction becomes.
What a risk system should detect
Looking only at individual stake size is insufficient. A sportsbook needs a market-wide view combining signals such as:
- a sudden rise in bet count;
- money concentrating on one outcome;
- identical selections across many accounts;
- divergence from external price references;
- unusual request velocity;
- links between devices, networks or behaviour where organised activity is reasonably suspected.
The last signal requires care. An identical selection does not make accounts connected. A popular tipster can direct thousands of independent customers to the same slip without shared devices, payments or ownership.
Responses should therefore operate at different levels. A pricing problem calls first for repricing or suspending the market. Excess exposure may justify reducing the available amount. Account investigations make sense when further evidence of connected activity exists.
Mass-restricting ordinary customers after the sportsbook’s own error is both crude and ineffective. By the time manual reviews begin, another wave may already have accepted the same price.
Why several sportsbooks can move together
A price move does not always begin with mass betting or prove that new event information exists. One sportsbook may react to an informed customer, while others copy the move because they use its line as a reference.
ESPN described a useful contrast in 2021. A professional group believed the WNBA All-Star Game total was far too high. Its first bet, however, was on the over through an account closely watched by sportsbooks. Circa raised the total, other operators followed, and only then did the group place its principal under bets at better numbers.
This is a different mechanism. In a WhatsApp community, one bet is copied rapidly by many people. In the WNBA case, a professional group used the market’s reaction to disguise its real direction and improve its price.
Both examples show why line movement is not proof of reliable new information. It can reflect a genuine probability change, an informed bettor, copying another line, mass imitation or correction of an original error.
Risk does not live only inside an account
It is easier to notice one customer requesting $2,000 than to interpret four hundred customers staking $20 at once. Yet economic risk is determined by total market liability, not by how threatening each ticket looks.
For bettors, this does not mean every selection from a popular group should be copied quickly. The price may already have changed, the original analysis may be wrong, and popularity says nothing about expected value.
For a trading team, the lesson is different: risk management cannot stop at personal limits and known professionals. The system must recognise when many completely ordinary wagers have effectively become one large sportsbook position.
Sources: iGamingBusiness — How trading teams can shape African sportsbooks, ESPN — The head-fake game.