 Alex Morgan
Can a Prediction Market Make the Event It Trades More Likely?
Polymarket lets traders buy contracts on whether HSBC, Lloyds, JPMorgan Chase, Deutsche Bank, BNP Paribas and other major banks will fail by the end of 2026.
Their existence raises an obvious moral question: should people profit from an event that could cost jobs, hurt depositors and destabilise the financial system? But there is a more complicated question. Can a prediction market merely measure expectations, or can it also influence the probability of the event it trades?
That effect is almost absent in a football match. A changing contract price will not make the players score or concede. Banks are different: their stability depends not only on capital, assets and liabilities, but also on customer confidence. If enough depositors decide to withdraw at once, fear can begin to create the very problem people feared.
The bank-failure markets on Polymarket
The Which banks will fail by end of 2026? group opened on 8 April 2026 and covers 19 banks in the US, UK, Canada and Europe.
According to The Guardian, the markets represented $77,507 in positions on 3 October. At 17:03 UTC on 4 October, Polymarket’s public API showed about $78,826 in cumulative volume, $17,618 in current liquidity and $14,448 in open interest.
These figures describe different things:
- volume adds up completed trades over the life of the markets;
- liquidity describes funds currently available in order-book quotes;
- open interest represents positions that remain open.
It would therefore be misleading to say that almost $79,000 was simply “bet on bank failures”. Volume includes both sides of a contract, and the same position can change hands several times.
What prices showed on 4 October
This snapshot comes from Polymarket at 17:03 UTC on 4 October 2026. Prices and available amounts change as orders and trades arrive.
| Bank | Indicative Yes price | Cumulative volume | Current liquidity |
|---|---|---|---|
| Deutsche Bank | 1.5% | $10,290 | $1,118 |
| Lloyds | 1.7% | $9,168 | $1,204 |
| HSBC | 2.4% | $2,023 | $946 |
| JPMorgan Chase | 1.9% | $839 | $173 |
| BNP Paribas | 2.9% | $646 | $701 |
View the current Polymarket data
A Yes contract price can look like a ready-made probability. A price of 2.4 cents is commonly read as roughly a 2.4% estimate. Yet it is only indicative. There is a best bid and ask, a spread between them, and often little size available at either price.
At the time of the snapshot, the best bid for JPMorgan Yes was near 1%, while the best ask was around 2.8%. With that gap, the market had not produced one precise, robust probability.
Low liquidity matters here. A modest trade can move the displayed price substantially. A move from 1% to 2% can be reported as “the market doubled the chance of failure”, even if it happened on little volume inside a wide spread.
What counts as a bank failure
The contract does not resolve Yes merely because a share price falls, rumours circulate or withdrawals are temporarily delayed.
Under the Polymarket rules, a qualifying event includes:
- a regulator formally declaring the bank insolvent or non-viable;
- withdrawal of its licence followed by liquidation or resolution;
- a court or regulator imposing liquidation, resolution or an asset transfer;
- state intervention that wipes out or subordinates equity and transfers effective control;
- a regulator ordering a merger or transfer of substantially all assets and liabilities because of the bank’s financial condition.
Official regulator statements and actions are the primary resolution sources. If an event occurs before year-end but is not yet formally confirmed, the market may remain open until 30 April 2027.
Clear rules reduce settlement disputes. They do not eliminate the market’s potential influence before settlement.
When a forecast becomes part of the event
Prediction markets are usually presented as information-aggregation mechanisms. One trader studies bank accounts, another follows credit protection prices and a third understands regulators. Their trades combine those views into a price.
In that model the market observes the outside world and updates when new information arrives. For some events, however, the relationship can run both ways:
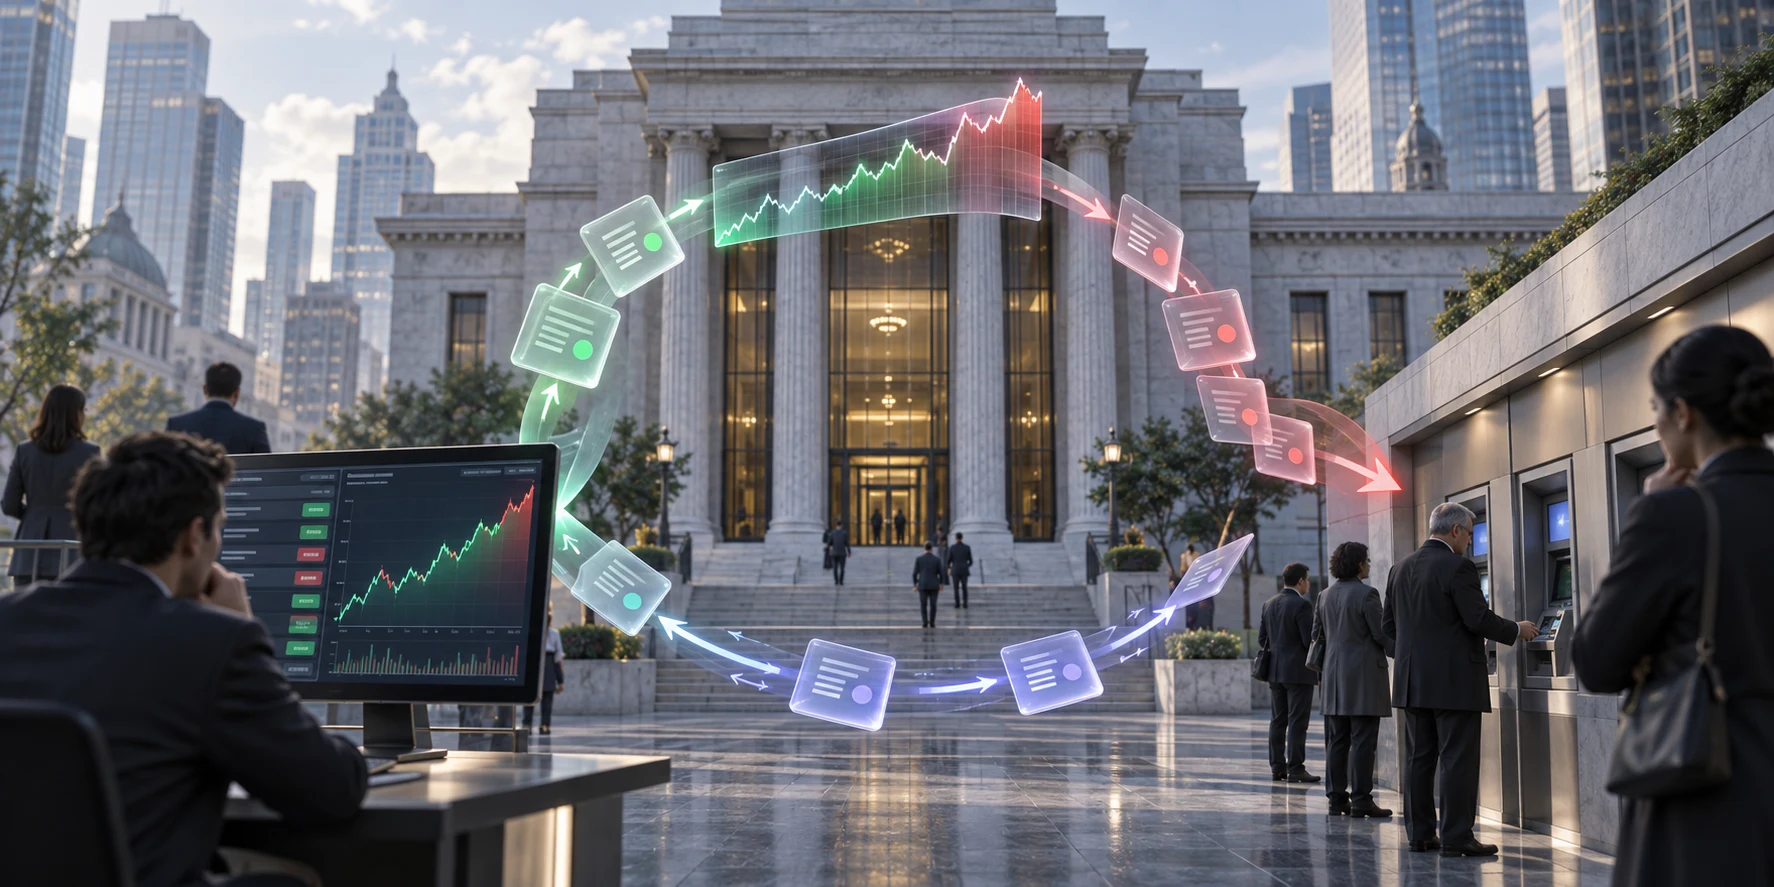
concern about a bank rises → the Yes price increases → social media and news outlets notice → customers grow nervous → withdrawals accelerate → the bank’s position actually weakens
This is reflexivity: expectations do not only describe reality; they change the behaviour on which the eventual outcome depends.
A bank run is an especially clear example. A bank may own enough assets but be unable to turn them into cash immediately without losses. If too many customers demand their deposits at once, a confidence problem quickly becomes a liquidity problem.
In 2023, the crises around Silicon Valley Bank and Credit Suisse unfolded amid rumours and concerns spreading rapidly through X, WhatsApp and other digital channels. Social media was not the sole cause, but it showed how modern information flows can accelerate an outflow already under way.
A prediction market adds another element to that flow: a number that looks like a collective probability estimate.
Why a small market can still become visible
Almost $79,000 in volume is immaterial beside the balance sheets of major banks. These trades cannot directly change their financial condition.
The possible effect comes from distribution of the price, not the size of the contracts. A headline saying “the probability of a bank failure doubled” may reach a much larger audience than the market itself. Most readers will not see the order book, spread, liquidity or trade size that moved the price.
That creates a gap between the market’s financial weight and the informational weight of its headline number. An illiquid contract may be economically tiny while its movement becomes an easy percentage to circulate online.
The reverse is also possible. A low Yes price may reassure people and indicate that traders see little danger. Prediction markets do not necessarily amplify only panic. The problem begins when a price is presented as an objective forecast without its liquidity, available size and bid-ask spread.
Can someone deliberately move the probability?
In theory, a participant could buy Yes contracts in an illiquid market, lift the displayed price and then promote that movement as an independent sign that a bank is deteriorating.
The economic logic would differ from an ordinary attempt to make a correct prediction. A trade could be used to create an information event, while any larger benefit might sit outside Polymarket in another financial position.
There is no evidence that this has happened in the listed bank markets. There is currently no proof that their prices caused withdrawals, affected the stability of a bank or were deliberately moved to create panic. This is a potential feedback loop, not an established event.
Why regulators are paying attention
The Financial Conduct Authority told The Guardian that it was discussing prediction markets with international regulators as part of its work to protect market integrity.
In its regulatory perimeter report, the FCA distinguishes contracts tied to financial events from sports or political markets. Its current view is that financial prediction-market products may constitute binary options, whose sale to UK retail consumers is prohibited.
This is why the issue is not only a debate about acceptable betting topics. A sports contract observes a match. A contract on the failure of a systemically important bank intersects with financial stability, sensitive information and market-manipulation rules.
Polymarket argues that it makes bank-risk information available to a wider audience. Professional participants have long used credit default swaps and other instruments to assess corporate and bank risk. A public Yes/No contract does simplify complex financial information.
But that simplicity also removes context. A price in cents is easier to understand than a credit spread, yet it hides market depth, participant quality, the bid-ask spread and how much trading would be required to move the price.
A market can measure fear and amplify it at the same time
Polymarket’s bank contracts remain small. Their prices are not evidence that the listed banks are about to fail, and available liquidity is too limited to treat every percentage-point move as a reliable signal.
The structure still deserves attention. When an outcome depends on the behaviour of many people, a forecast can become part of the causal chain.
A prediction market may be the first place to notice a genuine problem. It may also exaggerate a weak signal because liquidity is low. Once its price circulates beyond the platform, it can influence the expectations of people whose actions have real consequences.
The central question is therefore not whether people should be allowed to take a position on a bank failure. It is how to distinguish useful information aggregation from an indicator that begins to change the event it was designed to measure.
There is no basis for claiming that Polymarket has already brought any bank closer to failure. But these contracts reveal a new problem for prediction markets: sometimes a price stops being only a forecast and becomes information capable of influencing its own outcome.